

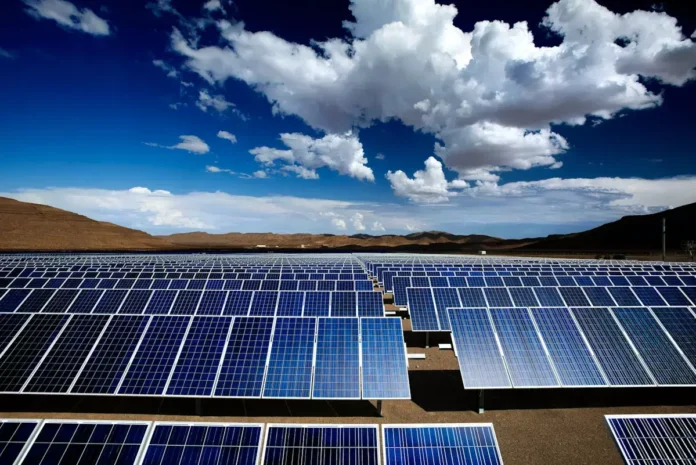
Chad has reached financial close on two hybrid solar power plants with a combined capacity of 30 MWp and 8 MWh of battery storage, backed by a €37.9 million financing package from development finance institutions.
Developed by independent power producer Qair at Gassi and Lamadji near N’Djamena, the projects will supply electricity to Chad’s national grid under a 20-year power purchase agreement with state-owned utility Tchadelec.
The African Development Bank said on September 25 that financial close had been reached and the first disbursement made, allowing construction to proceed.
The financing was arranged and mobilised by the AfDB Group with participation from Proparco, the Sustainable Energy Fund for Africa and the Green Climate Fund.
An €8 million partial risk guarantee jointly issued by the African Development Fund and the GCF supports a letter of credit covering Tchadelec’s payment obligations under the power purchase agreement.
According to Proparco, the French development finance institution and the AfDB are each providing about €15 million in loans. SEFA, managed by the AfDB, is contributing €6 million through reimbursable grants, while Proparco and the French Development Agency are providing additional support.
The wider financing package totals €37.9 million.
The financing structure addresses a major challenge for renewable energy investment in markets such as Chad: making technically viable projects bankable while managing currency, utility credit and political risks.
The guarantee is designed to address a key concern for investors — whether the electricity buyer can meet its contractual payment obligations.
The Gassi and Lamadji plants will connect to N’Djamena’s 90-kilovolt electricity network. Their 8 MWh battery systems will help manage the injection of solar power into the grid.
Proparco said the plants will connect to the capital’s 90 kV loop and incorporate 8 MWh of battery storage.
The investment comes as Chad faces a severe electricity-access deficit. World Bank data show that only 13.4% of the population had access to electricity in 2024, leaving the country among Africa’s least electrified economies.
Chad has substantial solar resources, with global horizontal irradiation ranging from about 5.8 kWh per square metre per day in the south to 6.8 kWh in the North. However, those resources remain relatively underused in the electricity system.
N’Djamena faces particular infrastructure constraints. Earlier World Bank assessments described the capital’s power system as heavily dependent on liquid-fuel generation, with installed capacity of about 150 MW at the time and persistent supply constraints.
The utility has also faced financial and operational limitations that make investment in new generation and network infrastructure difficult.
The new projects therefore represent more than an additional 30 MW of generation. They are an attempt to increase renewable power in a system where reliability, affordability and electricity access remain major development challenges.
Improved electricity supply can affect operating hours, refrigeration, communications, health services and the cost of running businesses. The World Bank has previously documented how limited electricity access constrains economic activity in Chad, while its more recent energy-access programme has sought to expand both grid and off-grid solar solutions.
The projects are also linked to two wider African energy initiatives. The AfDB’s Desert to Power programme aims to develop 10,000 MW of solar generation across the Sahel, while Mission 300 seeks to accelerate electricity connections across Africa.
The Chad transaction illustrates the type of project needed to turn those regional ambitions into physical infrastructure.
For investors, however, the deal highlights why Africa’s renewable energy expansion depends on more than solar technology. Projects also require bankable power purchase agreements, credible utilities, predictable regulation, transmission infrastructure and mechanisms to reduce risks that private lenders cannot absorb alone.
This challenge is particularly pronounced across the Sahel, where countries face weak electricity systems, limited fiscal space, high perceived investment risk and significant climate vulnerability.
Development finance institutions can help bridge that gap through guarantees, concessional instruments and project-preparation support. These tools can redistribute risks and help attract private developers and commercial lenders to markets that might otherwise remain outside conventional investment mandates.
Battery storage is also becoming increasingly important to renewable energy project design. In grids with limited flexibility, storage can help manage fluctuations in solar output and improve the quality of electricity delivered to the network.
But storage alone cannot solve the wider infrastructure challenge. The value of new generation depends on transmission and distribution networks being able to deliver electricity to consumers and utilities having the financial capacity to maintain them.
For Chad and other low-access markets, the investment challenge therefore extends from generation to grid expansion, metering, collections and institutional reform.
The transaction also raises questions about whether blended finance can be scaled beyond individual projects. Africa’s electricity deficit requires thousands of projects across countries with different levels of political, currency and utility risk.
Replicating the model will depend on whether development institutions can standardise risk-sharing mechanisms while retaining enough flexibility to address country-specific conditions.
The structure also has implications for public finances. Renewable projects can reduce exposure to volatile fuel costs over time, but long-term power purchase agreements can create obligations for state-owned utilities and governments.
The quality of those contracts, the financial health of the off-taker and the transparency of contingent liabilities will therefore remain important in determining whether renewable investment strengthens or puts additional pressure on public balance sheets.
For the Sahel, where climate pressures and development needs increasingly intersect, the investment case goes beyond emissions reduction. Reliable electricity supports industrial activity, digital services, water systems, health facilities and agricultural value chains.
The World Bank’s energy-access programmes in Chad have similarly combined grid expansion with standalone solar and storage solutions, reflecting the need for multiple technologies and financing channels.
The Gassi and Lamadji projects will not resolve Chad’s electricity deficit on their own. Their significance lies in showing how renewable energy projects can combine long-term contracting, battery storage, development finance and risk guarantees.
If similar structures can be replicated while utilities and transmission systems are strengthened, they could help move renewable energy investment in the Sahel from isolated projects towards a more durable infrastructure market.
Africa has some of the world’s strongest solar resources but continues to face a major gap between renewable-energy potential and investable electricity infrastructure.
Chad’s latest transaction shows that closing that gap will require not only more generation, but also financial structures and public institutions capable of making clean power projects credible to investors over the long term.
Source: africasustainabilitymatters
Do you want to share your impact stories or pitch the coverage of your CSR event to us? E-mail: editor@impactwatch.net or *Phone +234-806-795-0250 (Whatsapp &Text)


